
AI4Finance-Foundation/FinRL-Trading
AI4Finance-Foundation/FinRL-Trading has 3,909 GitHub stars and 1,134 forks. GitHot measured +3 stars in 24 hours. Last checked 2026-11-06 17:44 UTC. Last push 2026-09-18.
FinRL-X: An AI-Native Modular Infrastructure for Quantitative Trading
Measured star growth
- in 24h
- +3
- in 7 days
- Update delayed
- in 15 days
- Update delayed
- in 1 month
- Update delayed
Net star changes over overlapping periods, not daily totals. Missing measurements are left blank. Stars measure attention, not software quality.
README.md
OriginalFinRL-X
An AI-Native Modular Infrastructure for Quantitative Trading


A deployment-consistent trading system that unifies data processing, strategy composition, backtesting, and broker execution through a weight-centric interface.
Paper | Quick Start | Strategies | Results | Discord
About
FinRL-X is a next-generation, AI-native quantitative trading infrastructure that redefines how researchers and practitioners build, test, and deploy algorithmic trading strategies.
Introduced in our paper "FinRL-X: An AI-Native Modular Infrastructure for Quantitative Trading" (arXiv:2603.21330), FinRL-X succeeds the original FinRL framework with a fully modernized architecture designed for the LLM and agentic AI era.
FinRL-X is not just a library — it is a full-stack trading platform engineered around modularity, reproducibility, and production-readiness, supporting everything from ML-based stock selection and professional backtesting to live brokerage execution.
At its core is a weight-centric architecture — the target portfolio weight vector is the sole interface contract between strategy logic and downstream execution:
$$w_t = \mathcal{R}_t\bigl(\mathcal{T}_t\bigl(\mathcal{A}_t\bigl(\mathcal{S}t(\mathcal{X}{\le t})\bigr)\bigr)\bigr)$$
where $\mathcal{S}$ denotes stock selection, $\mathcal{A}$ portfolio allocation, $\mathcal{T}$ timing adjustment, and $\mathcal{R}$ portfolio-level risk overlay. Each transformation is contract-preserving — you can swap any module (e.g. equal-weight $\to$ DRL allocator) without touching the rest of the pipeline, and the same weights flow identically through backtesting and live execution.
Architecture
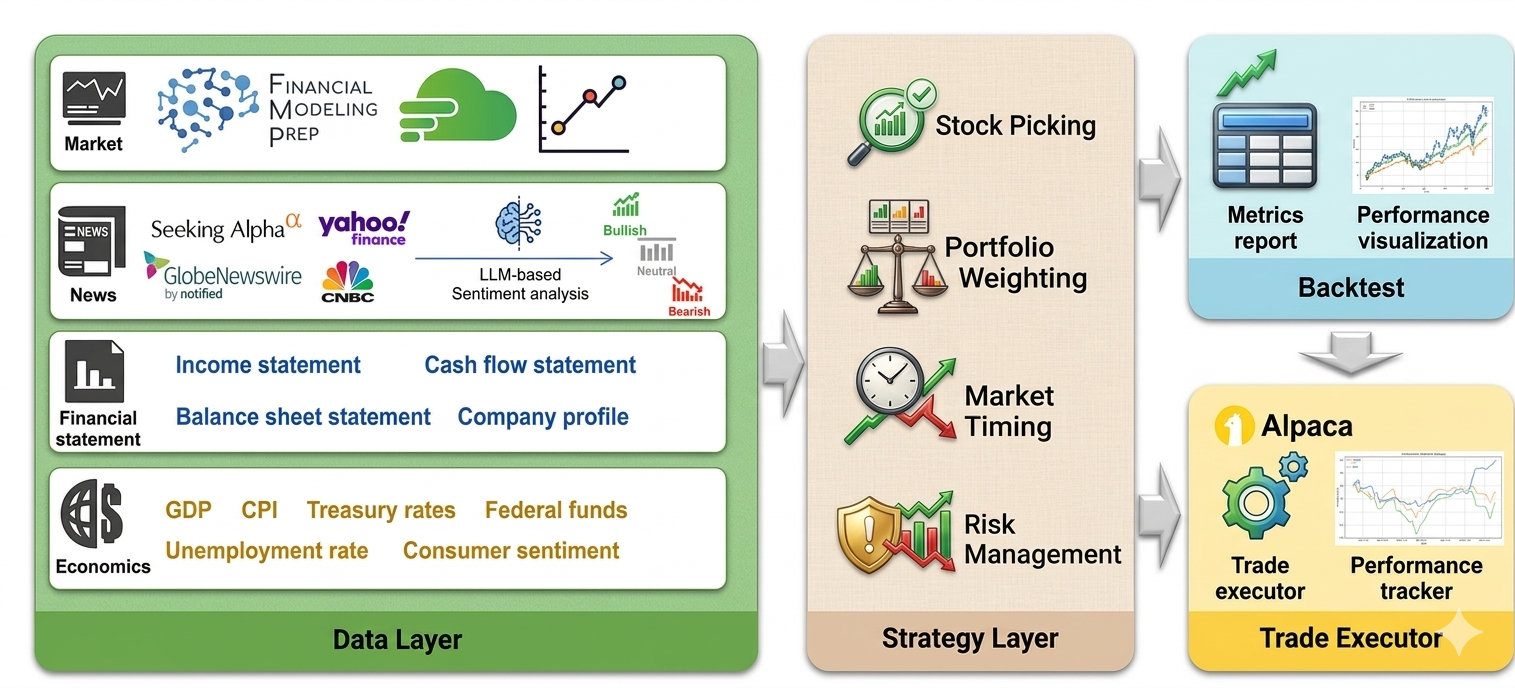
| Layer | Role | Components |
|---|---|---|
| Data | Unified market data pipeline | FMP, Yahoo Finance, WRDS; LLM sentiment preprocessing; SQLite cache |
| Strategy | Weight-centric signal generation | Stock selection, portfolio allocation, timing adjustment, risk overlay |
| Backtest | Offline evaluation | bt-powered engine with multi-benchmark comparison and transaction costs |
| Execution | Live/paper trading | Alpaca multi-account integration with pre-trade risk checks |
finrl-trading/
├── src/
│   ├── config/                     # ⚙️  Centralized configuration management
│   │   └── settings.py             #     Pydantic-based settings + environment variables
│   ├── data/                       # 🗄️  Data acquisition and processing
│   │   ├── data_fetcher.py         #     Multi-source integration (Yahoo / FMP / WRDS)
│   │   ├── data_processor.py       #     Feature engineering & data cleaning
│   │   └── data_store.py           #     SQLite persistence with caching
│   ├── backtest/                   # 📊  Backtesting engine
│   │   └── backtest_engine.py      #     bt-powered engine with benchmark comparison
│   ├── strategies/                 # 🤖  Trading strategies
│   │   ├── base_strategy.py        #     Abstract strategy framework
│   │   └── ml_strategy.py          #     Random Forest stock selection
│   ├── trading/                    # 💰  Live trading execution
│   │   ├── alpaca_manager.py       #     Alpaca API integration (multi-account)
│   │   ├── trade_executor.py       #     Order management & risk controls
│   │   └── performance_analyzer.py #     Real-time P&L tracking
│   └── main.py                     # 🚀  CLI entry point
├── examples/
│   ├── FinRL_Full_Workflow.ipynb   # 📓  Complete workflow tutorial (start here!)
│   └── README.md
├── data/                           # Runtime data storage (gitignored)
├── logs/                           # Application logs (gitignored)
├── requirements.txt
└── setup.py
Strategies
FinRL-X implements three use cases from the paper, each demonstrating different compositions of the weight-centric pipeline.
Use Case 1 — Portfolio Allocation Paradigms
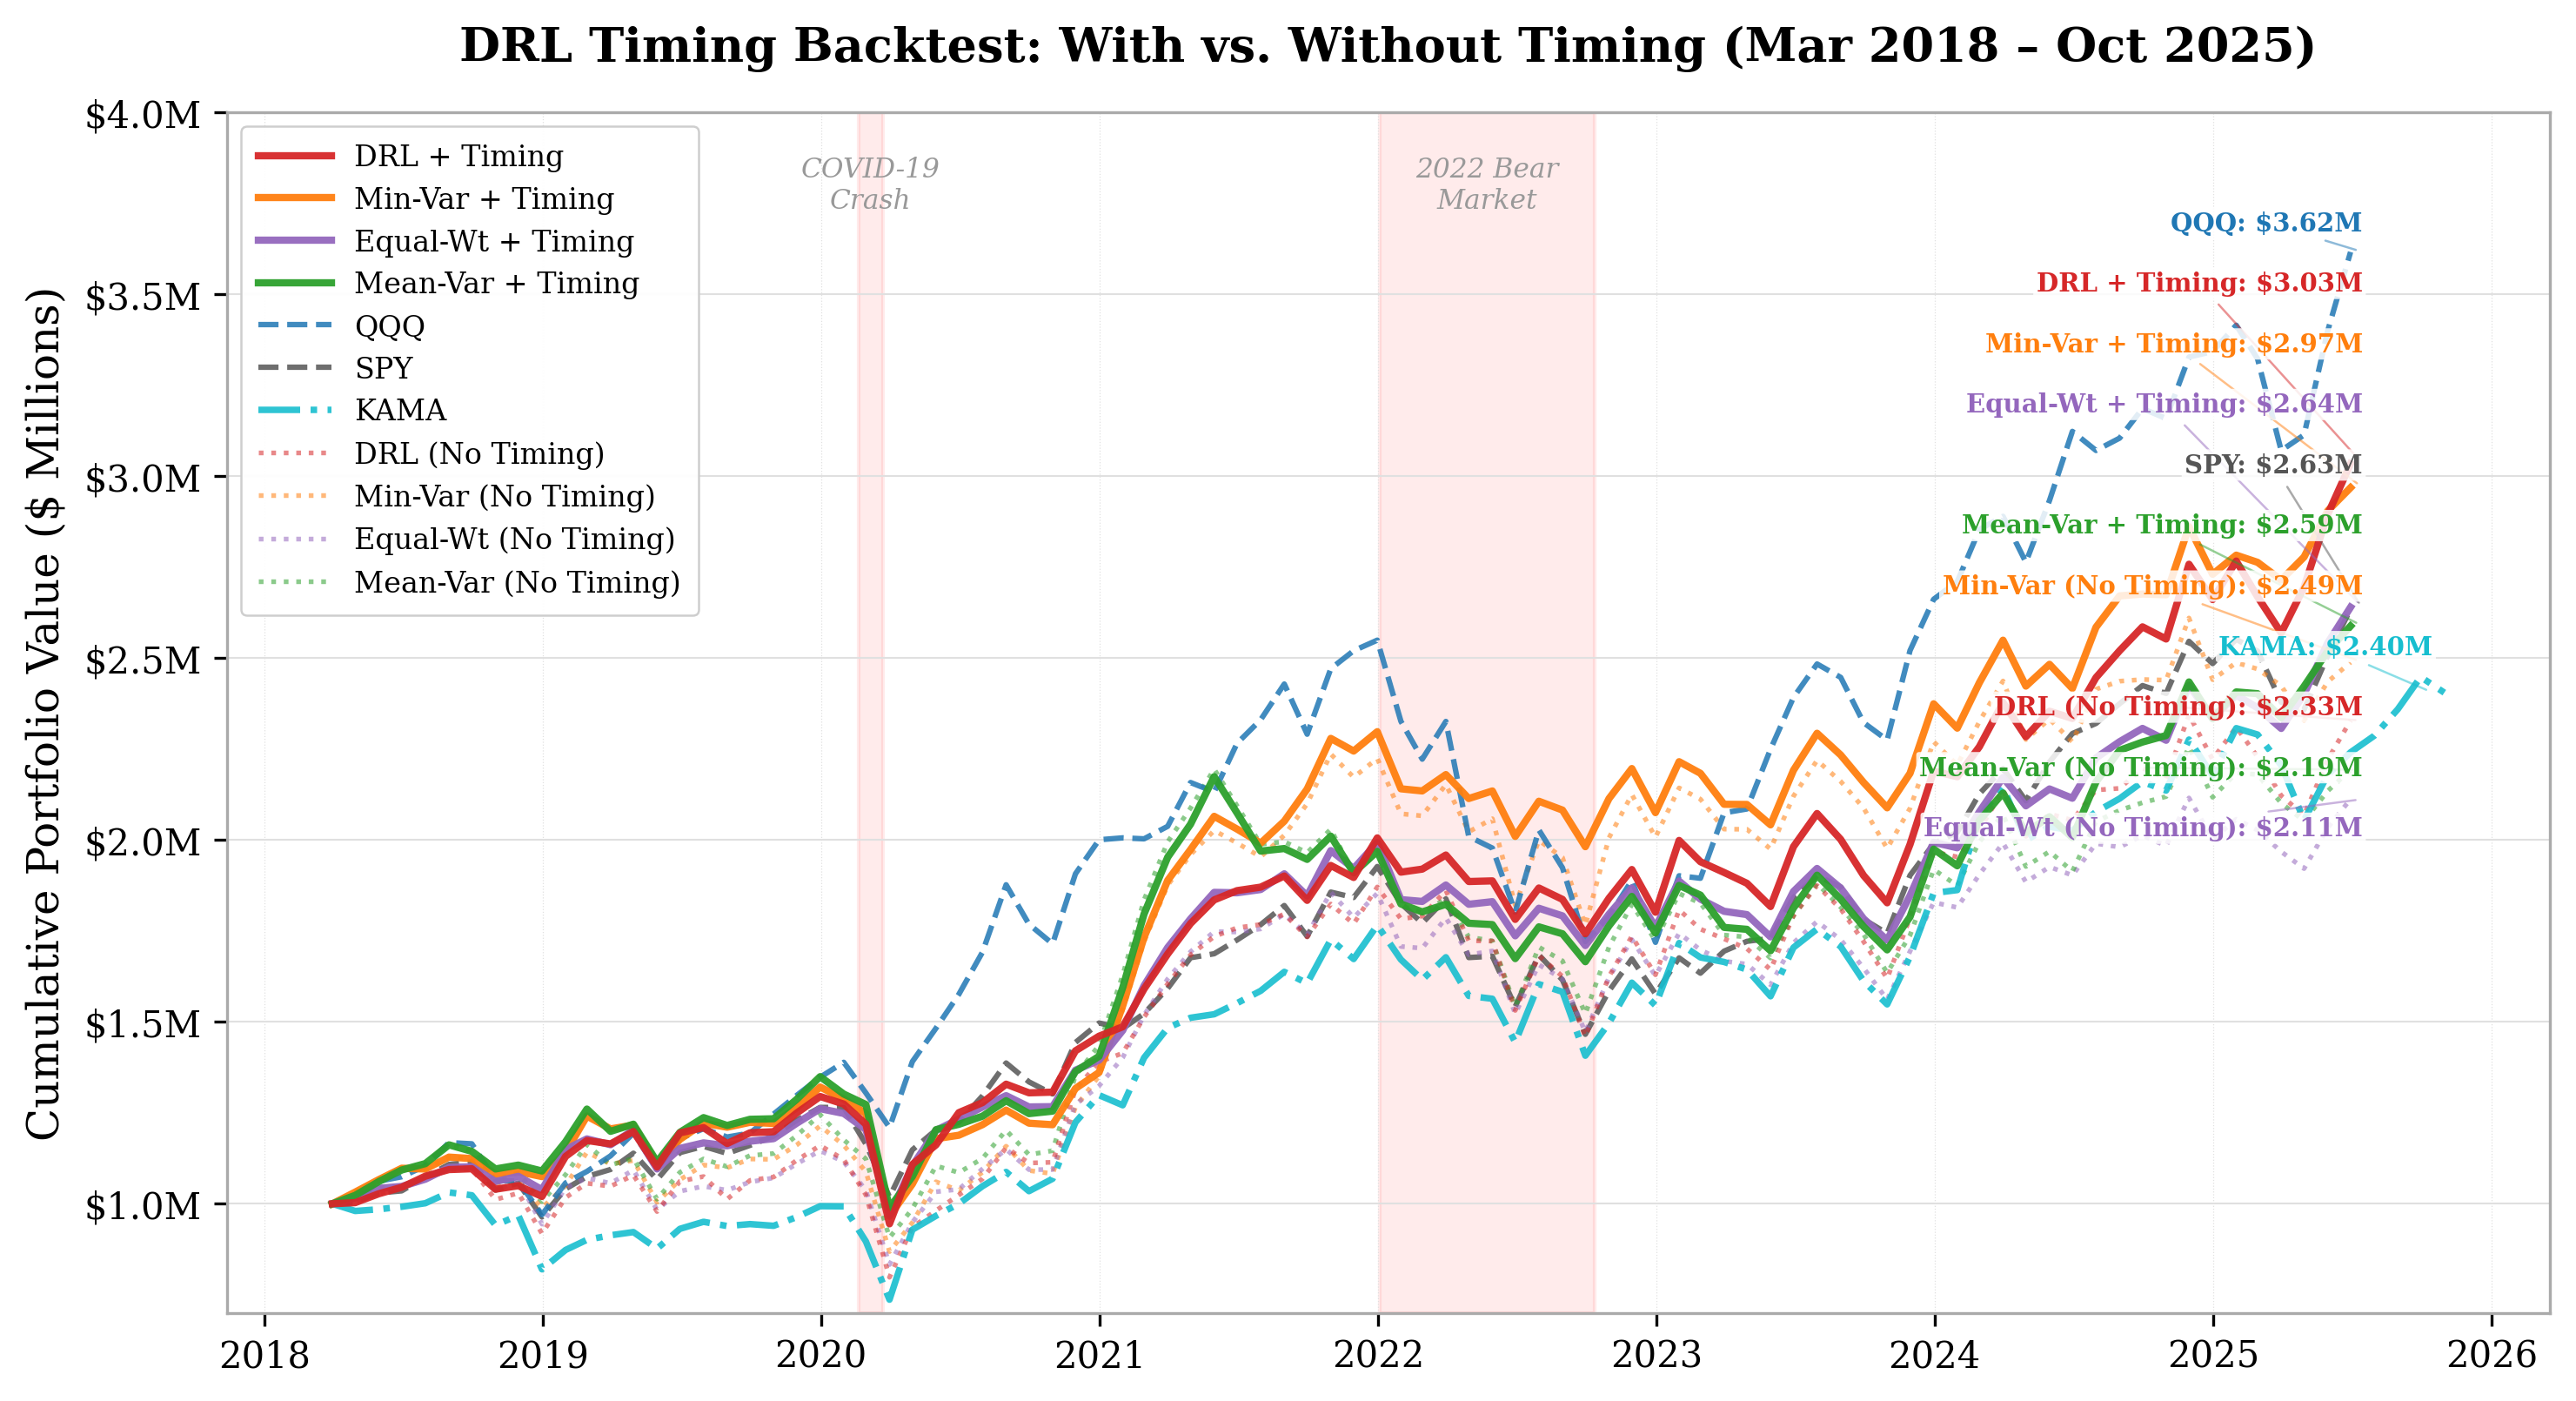
Compares heterogeneous allocation methods under a unified interface:
| Method | Type | Description |
|---|---|---|
| Equal Weight | Classical | Uniform 1/N allocation |
| Mean-Variance | Classical | Markowitz optimization |
| Minimum Variance | Classical | Minimize portfolio volatility |
| DRL Allocator | Learning | PPO/SAC continuous weight generation |
| KAMA Timing | Signal | Kaufman adaptive trend overlay |
All methods output the same weight vector, making them directly composable with timing and risk overlays.
Use Case 2 — Rolling Stock Selection + DRL
Quarterly selection of top-25% NASDAQ-100 stocks via ML fundamental scoring, combined with DRL-based portfolio allocation. Strict no-lookahead semantics prevent data leakage.
Use Case 3 — Adaptive Multi-Asset Rotation
A research-grade, walk-forward-safe rotation strategy with daily risk monitoring:
| Component | Detail |
|---|---|
| Asset Groups | Growth Tech, Real Assets, Defensive — max 2 active per week |
| Group Selection | Information Ratio relative to QQQ benchmark |
| Intra-Group Ranking | Residual momentum with robust Z-score exception handling |
| Market Regime | Slow regime (26-week trend + VIX) + Fast Risk-Off (3-day shock) |
| Risk Controls | Trailing stop-loss, absolute stop-loss, cooldown periods |
| Rebalance | Weekly (full) + daily monitoring (fast risk-off, stop-loss adjustments) |
# Run the adaptive rotation backtest
./deploy.sh --strategy adaptive_rotation --mode backtest --start 2023-01-01 --end 2024-12-31

# Paper trade with Alpaca
./deploy.sh --strategy adaptive_rotation --mode paper --dry-run
Results
Historical Backtest (Jan 2018 – Oct 2025)
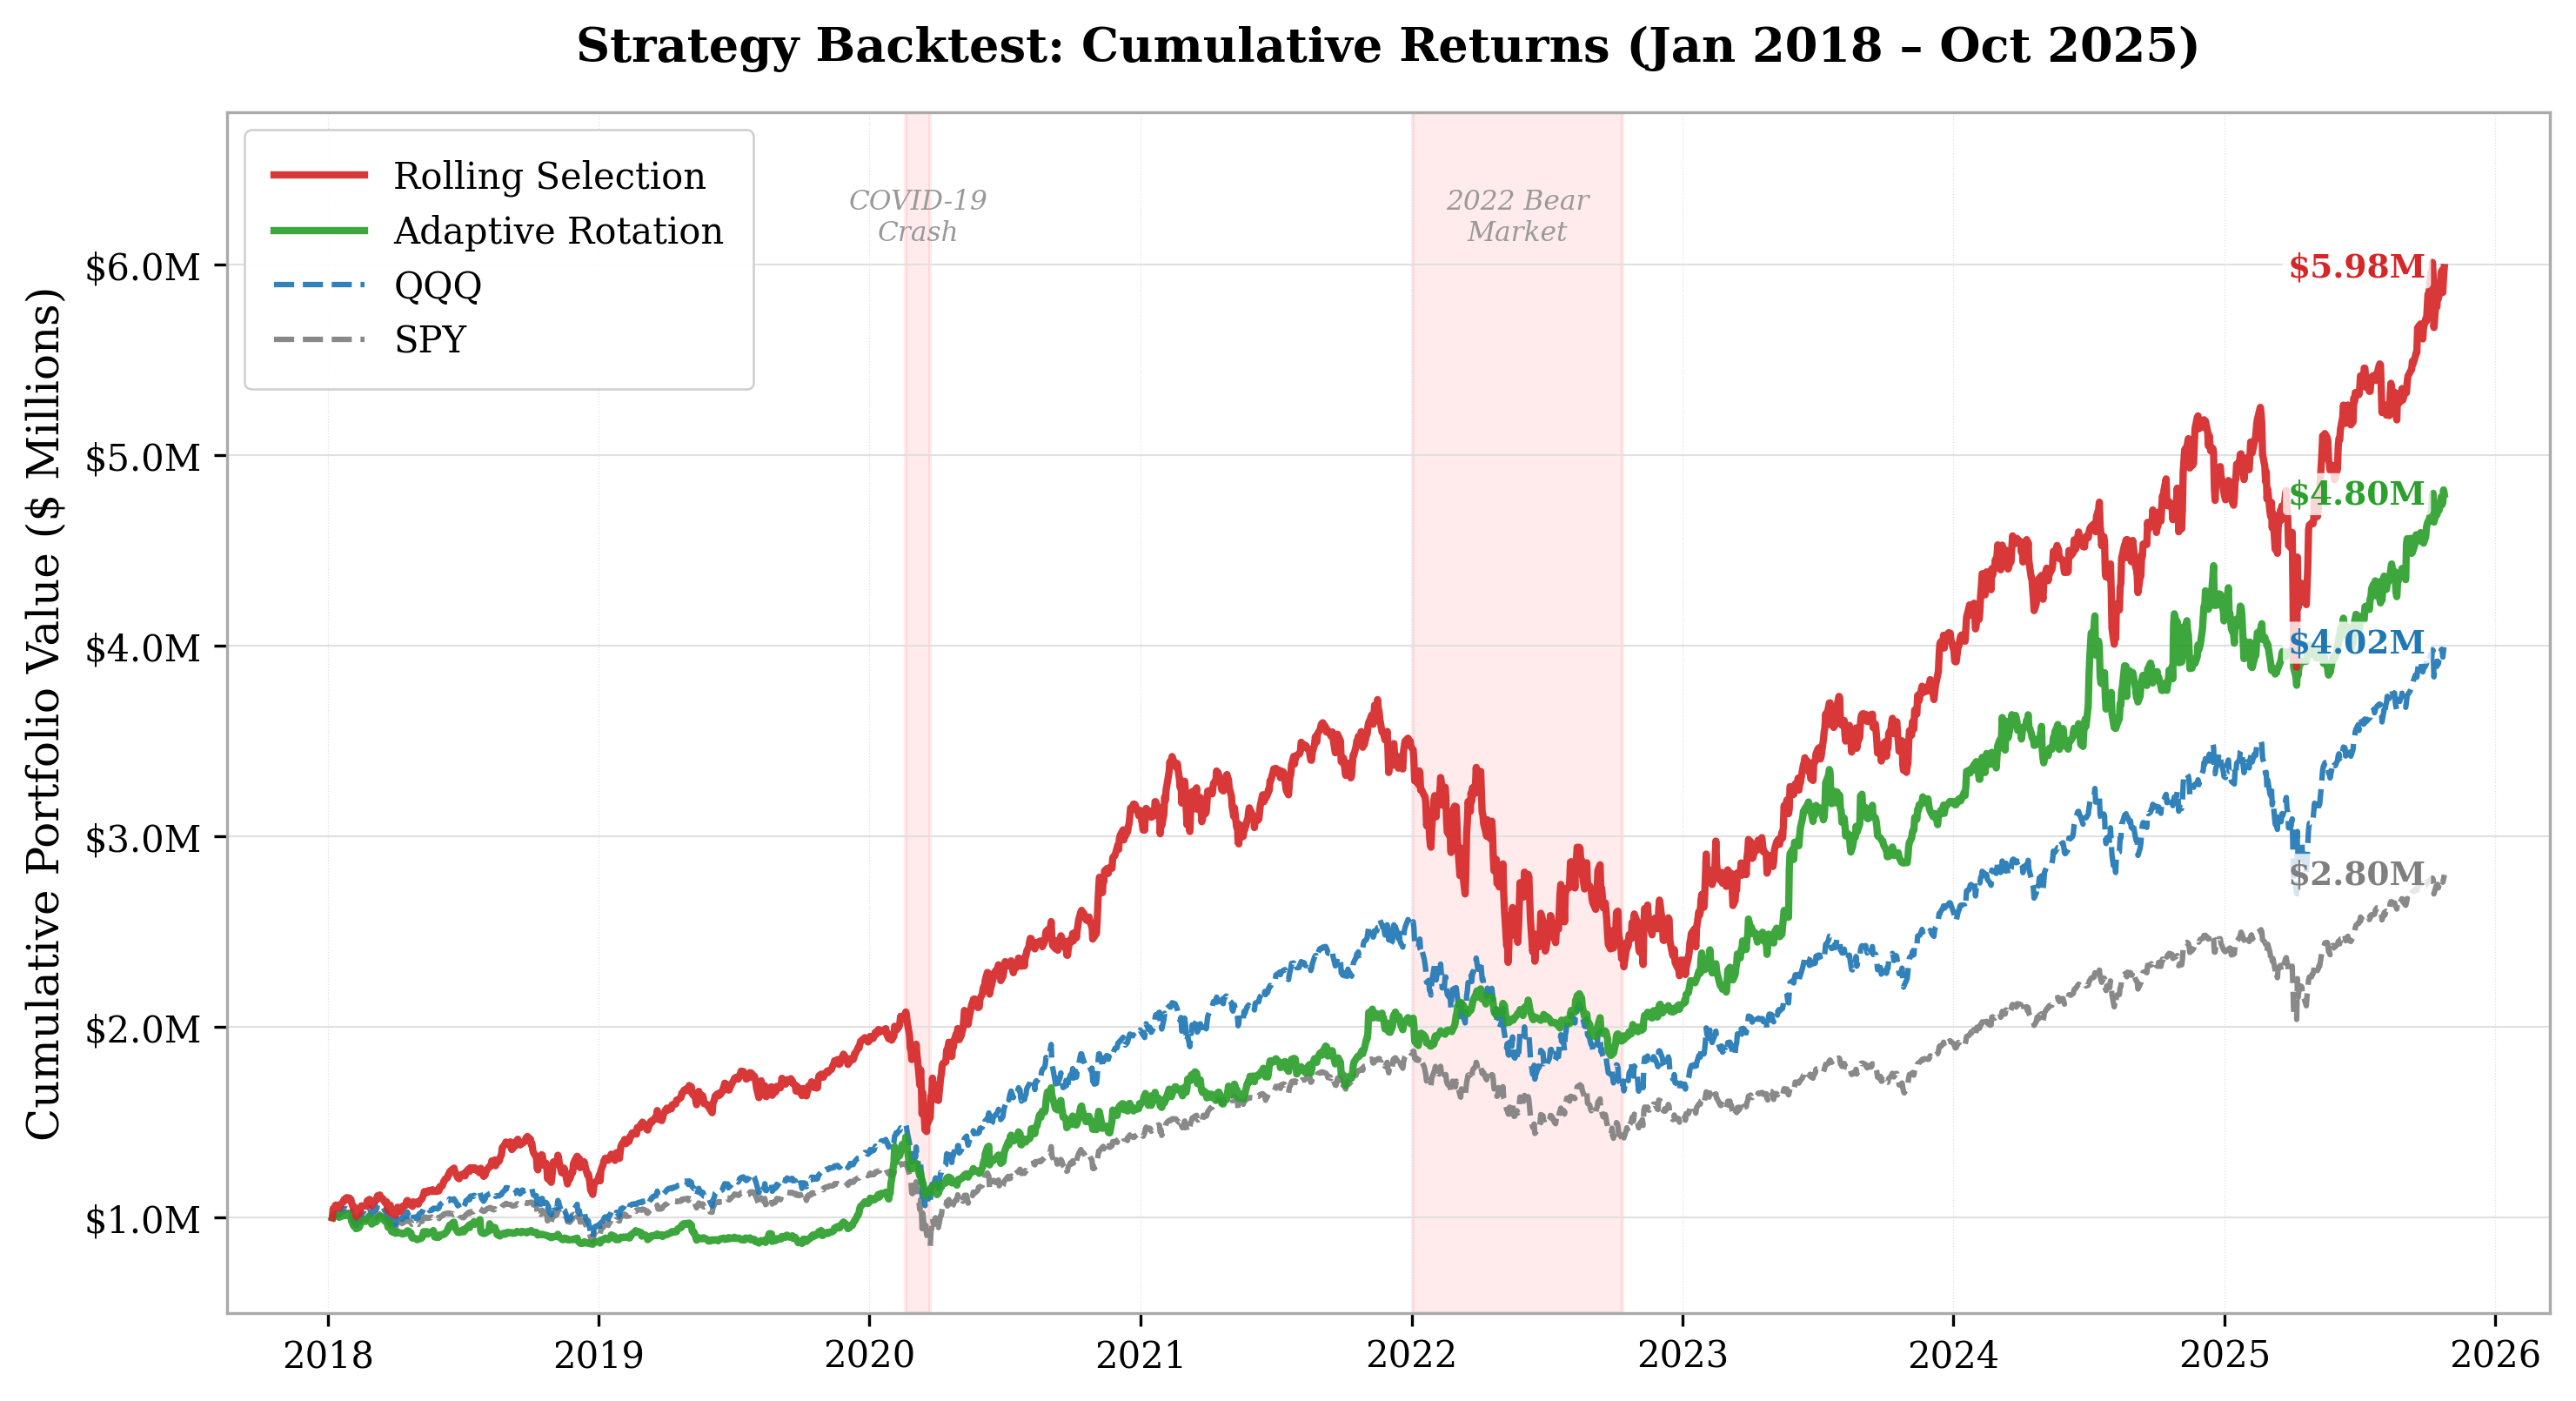
| Metric | Rolling Strategy | Adaptive Rotation | QQQ | SPY |
|---|---|---|---|---|
| Cumulative Return | 5.98x | 4.80x | 4.02x | 2.80x |
| Annualized Return | 25.85% | 22.32% | 19.56% | 14.14% |
| Annualized Volatility | 27.85% | 20.30% | 24.20% | 19.61% |
| Sharpe Ratio | 0.93 | 1.10 | 0.81 | 0.72 |
| Max Drawdown | -38.95% | -21.46% | -35.12% | -33.72% |
| Calmar Ratio | 0.66 | 1.04 | 0.56 | 0.42 |
| Win Rate | 54.36% | 54.77% | 56.25% | 55.28% |
Paper Trading (Oct 2025 – Mar 2026)
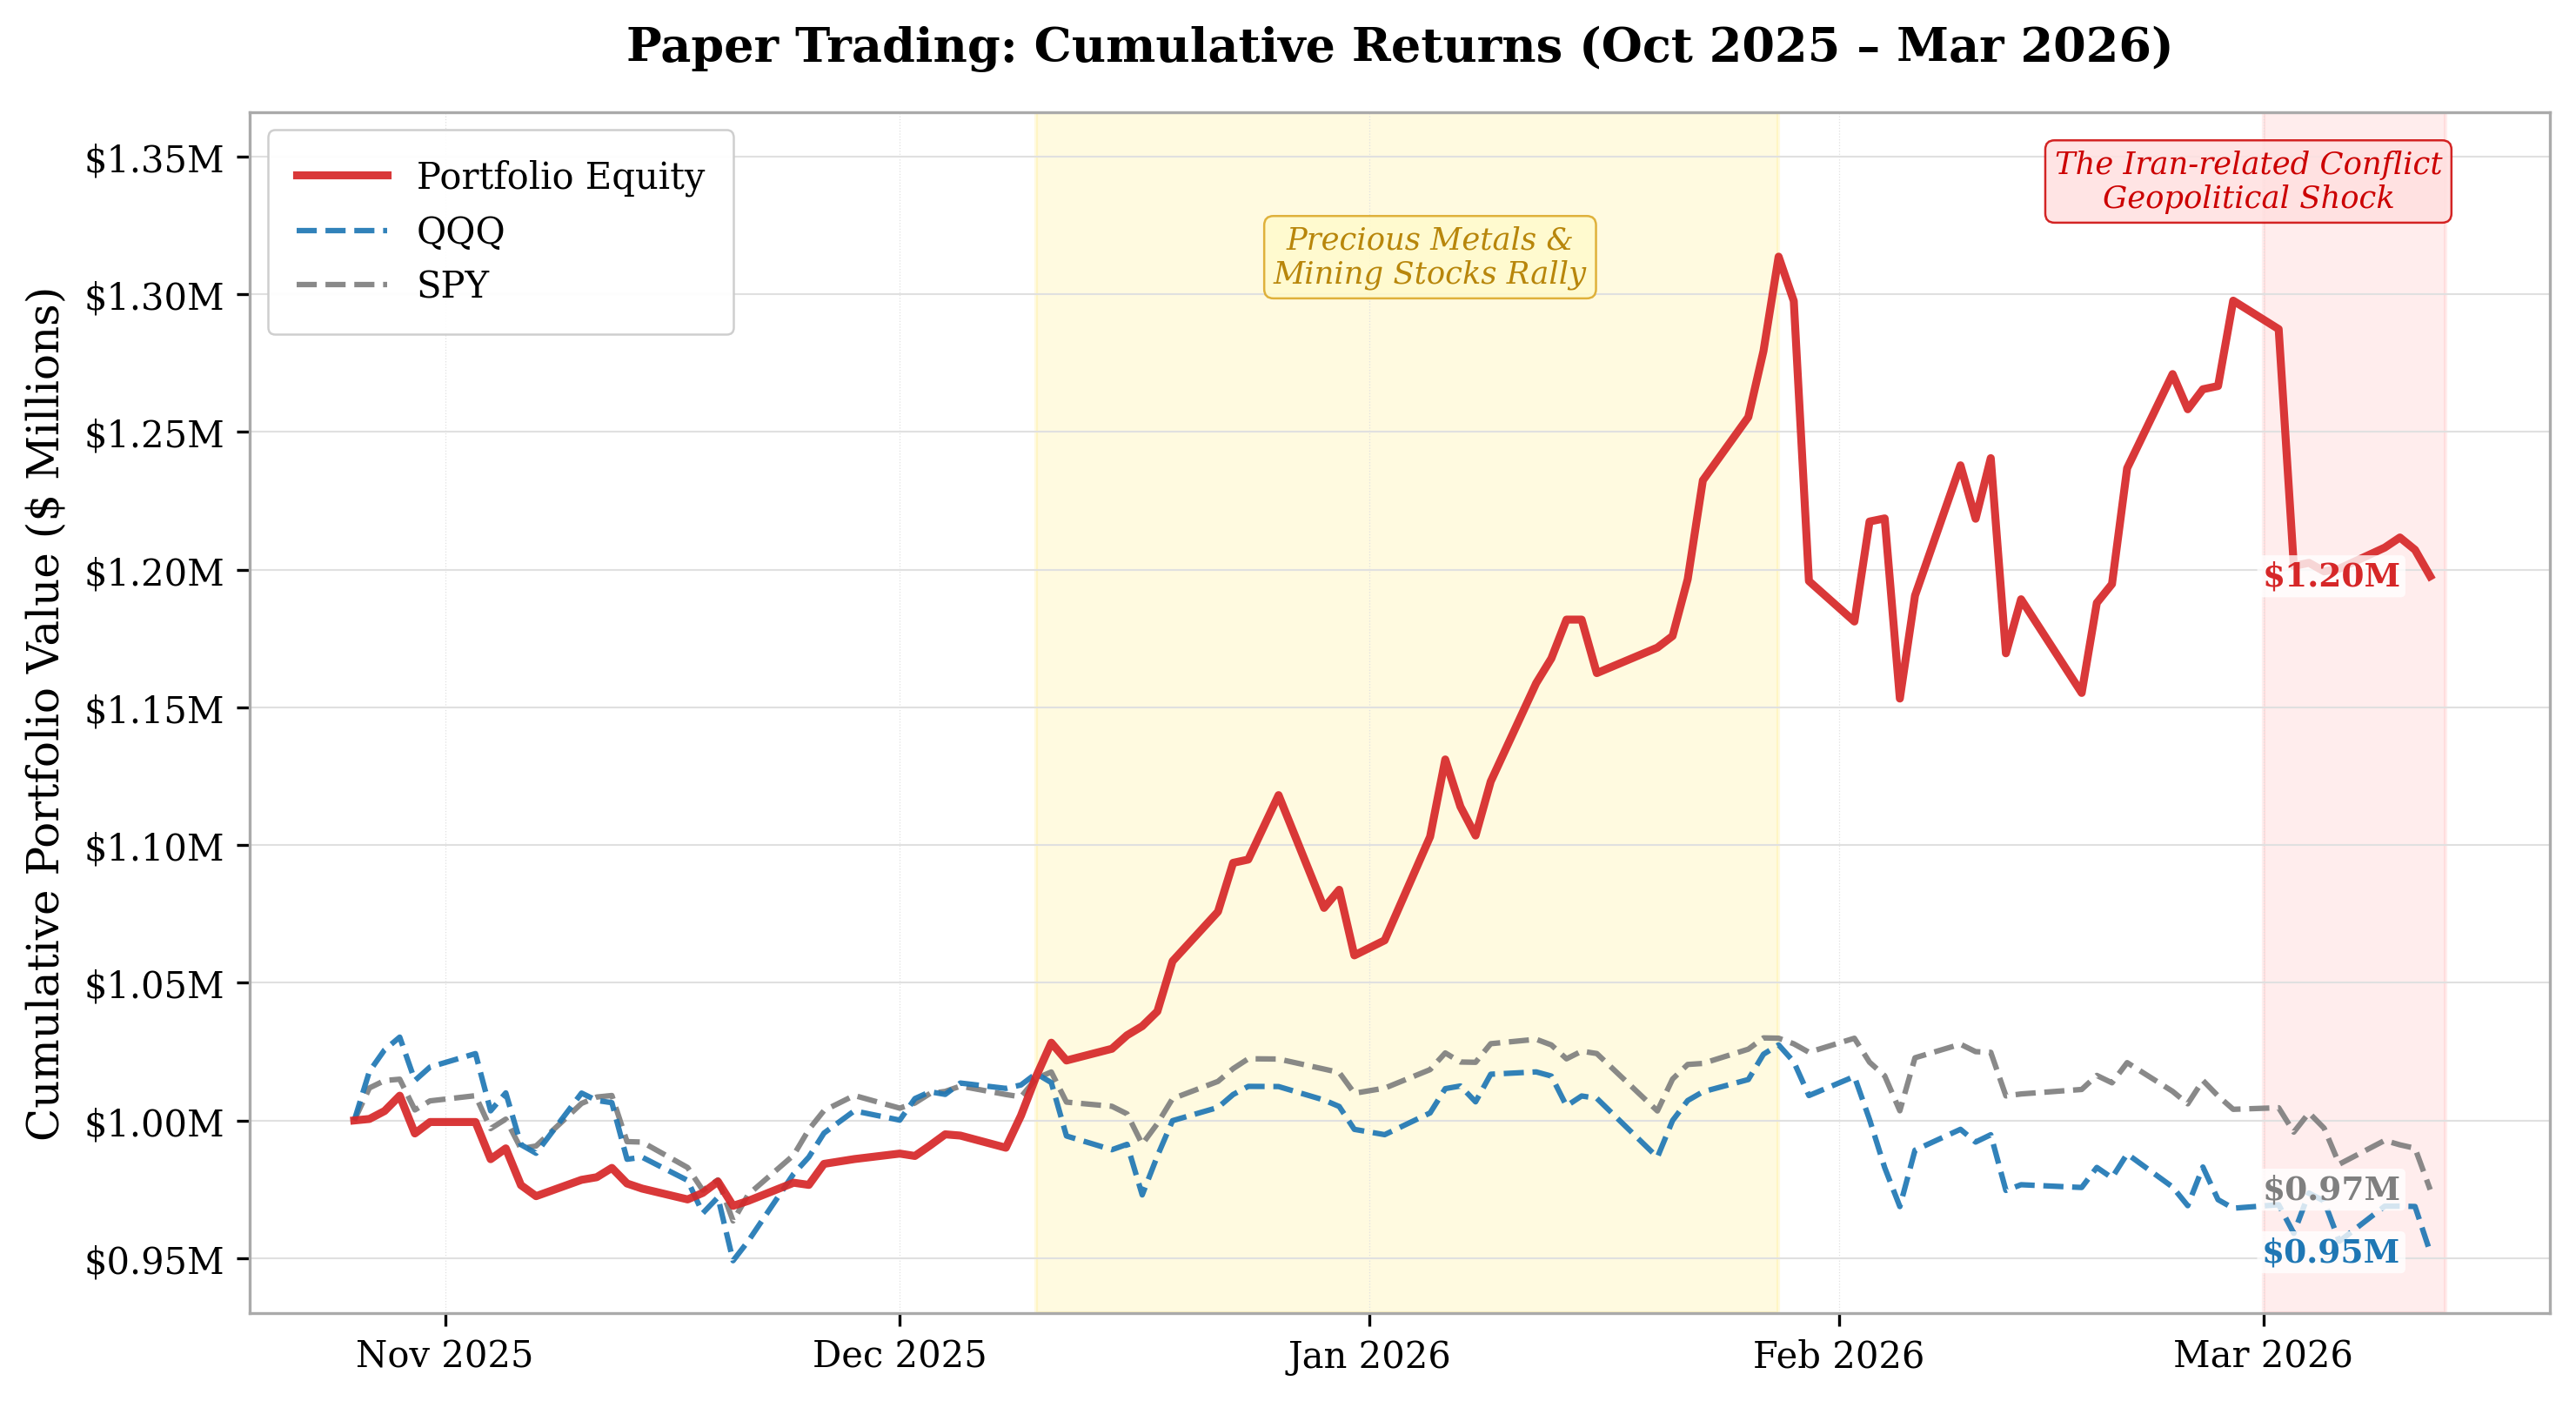
Ensemble of Rolling Selection + Adaptive Rotation deployed on Alpaca paper trading:
| Metric | Strategy | SPY | QQQ |
|---|---|---|---|
| Cumulative Return | 1.20x | 0.97x | 0.95x |
| Total Return | +19.76% | -2.51% | -4.79% |
| Annualized Return | 62.16% | -6.60% | -12.32% |
| Annualized Volatility | 31.75% | 11.96% | 16.79% |
| Sharpe Ratio | 1.96 | -0.55 | -0.73 |
| Max Drawdown | -12.22% | -5.35% | -7.88% |
| Calmar Ratio | 5.09 | -1.23 | -1.56 |
| Win Rate | 64.89% | 52.13% | 54.02% |
Dynamic Sector Rotation
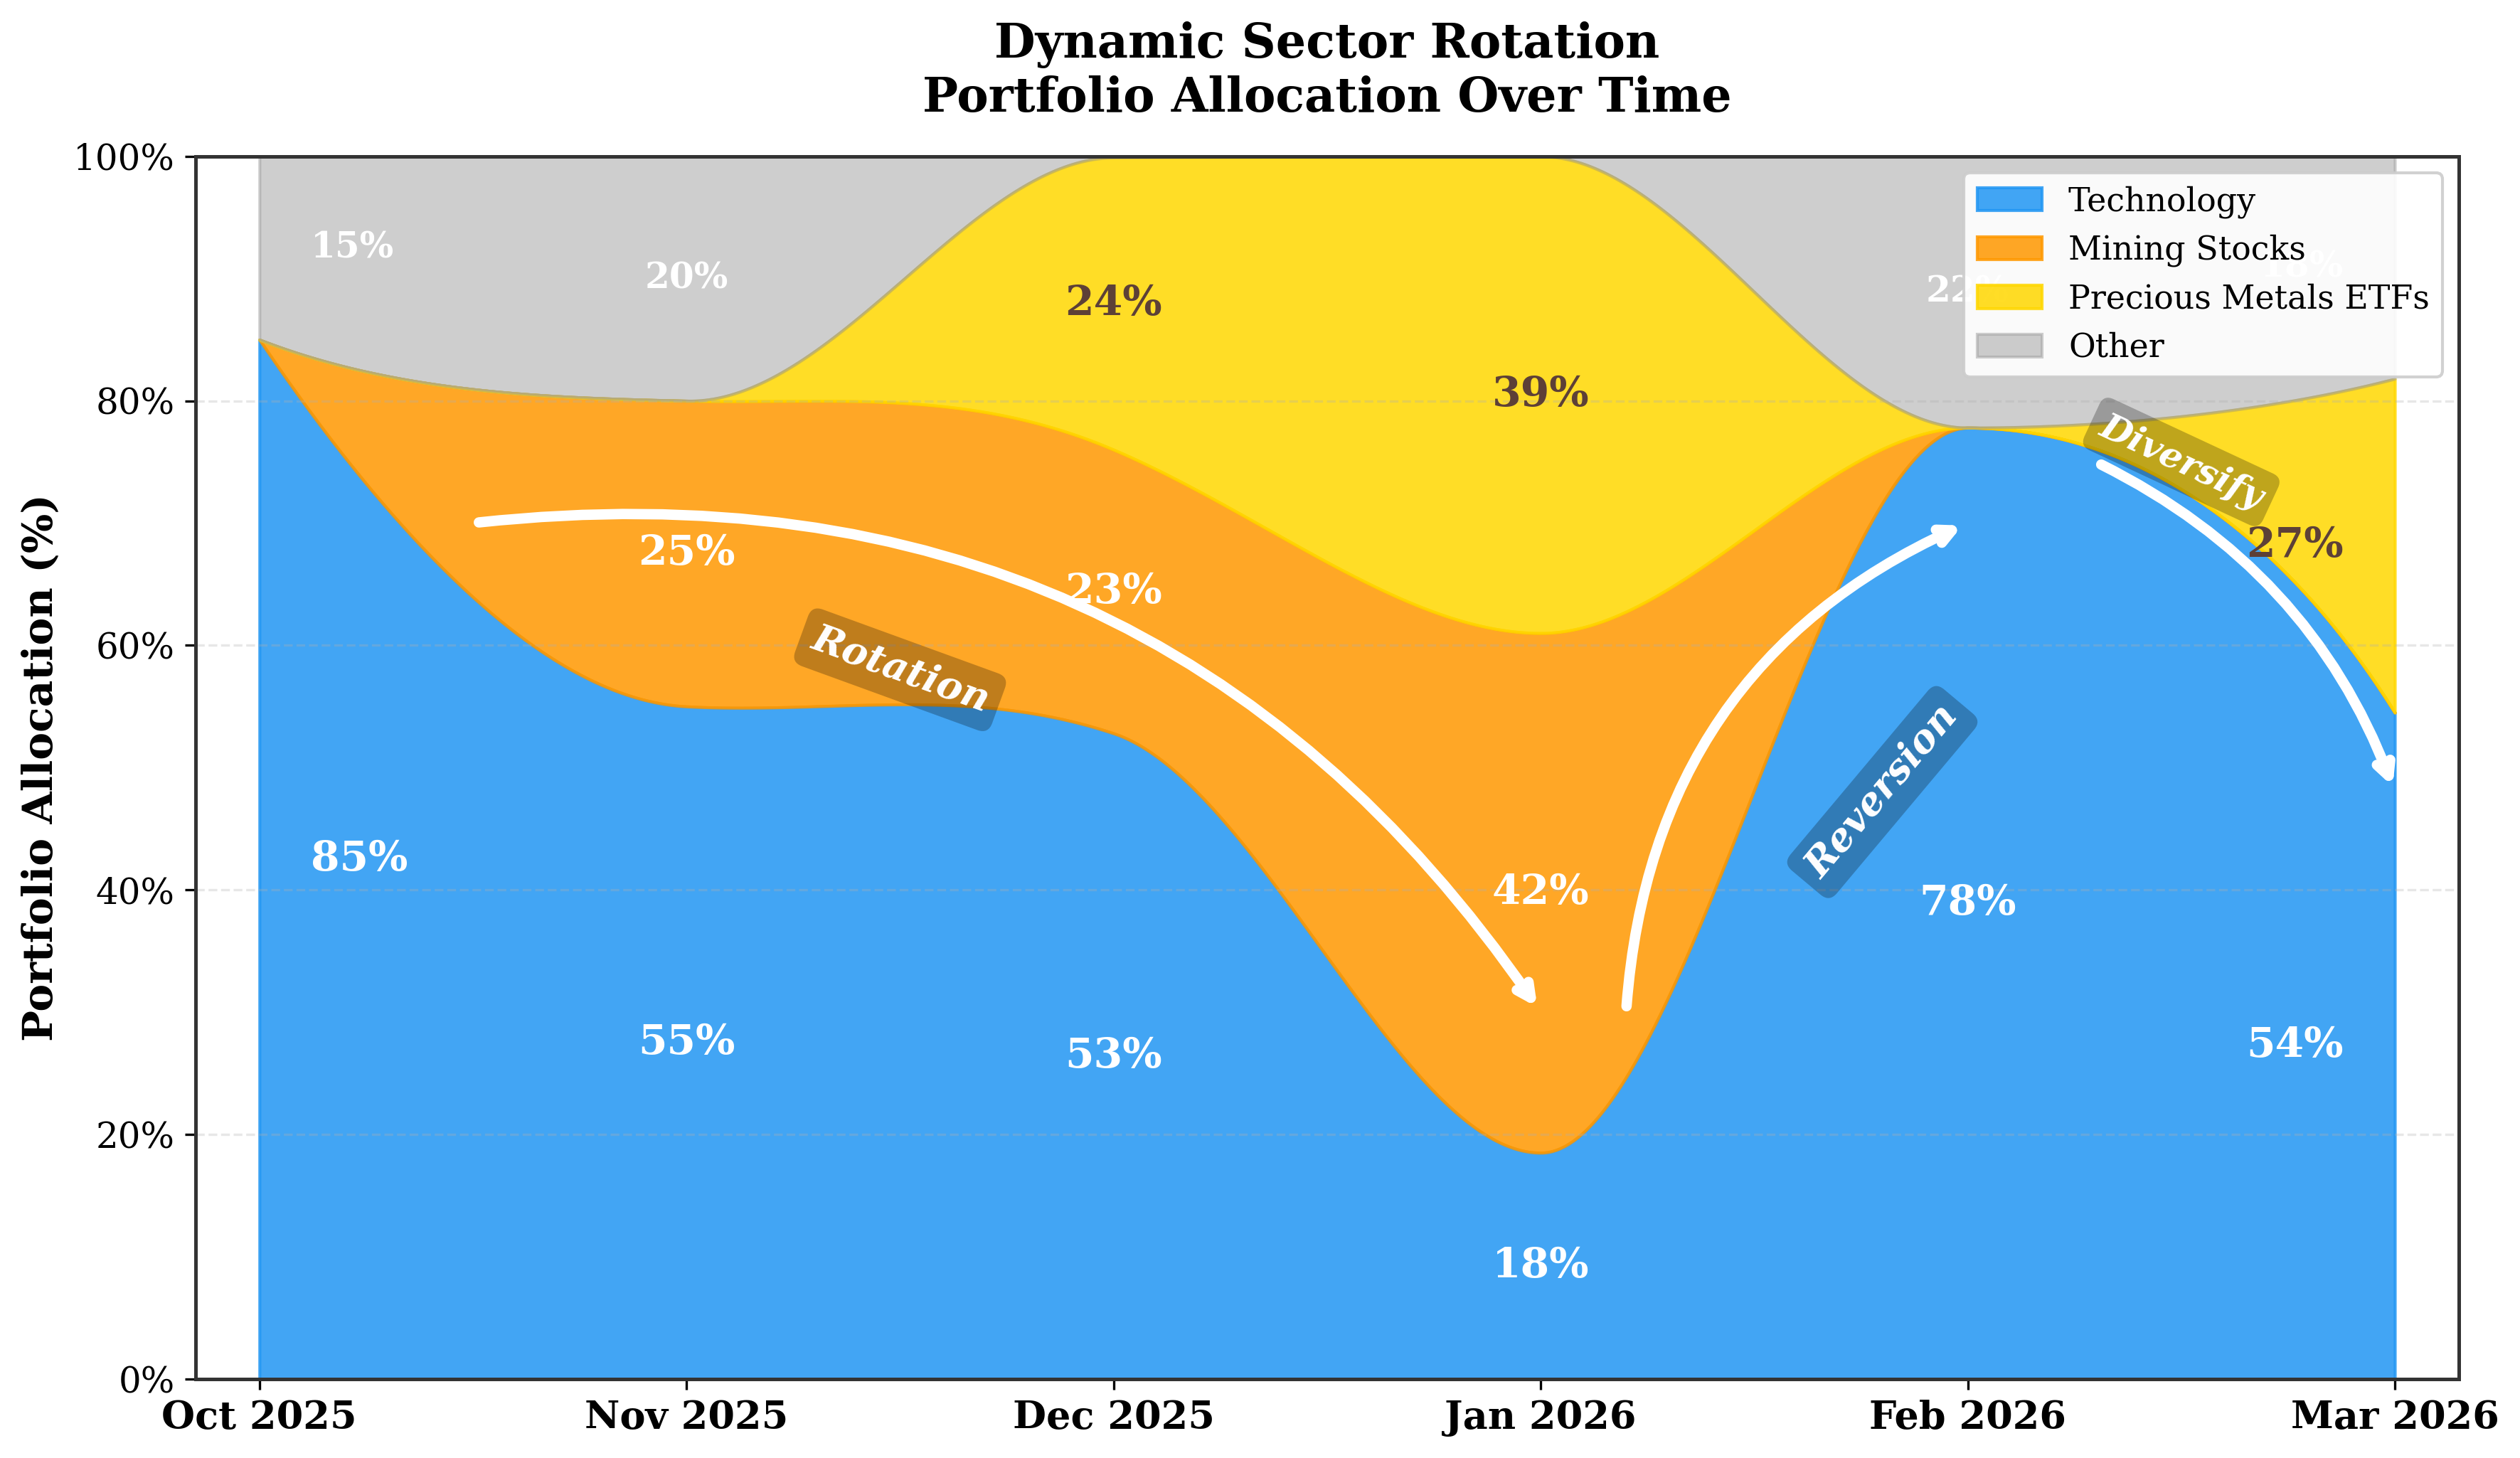
The Adaptive Rotation strategy dynamically shifts capital across three asset groups — Growth Tech, Real Assets, and Defensive — based on market regime signals. During risk-on regimes, the portfolio tilts toward high-momentum growth and commodity plays; when regime detection flags risk-off or fast risk-off conditions, capital rotates into bonds and utilities with an automatic cash buffer. Weekly rebalancing is complemented by daily stop-loss and fast risk-off monitoring, enabling rapid de-risking without waiting for the next scheduled rebalance.
Quick Start
Option A — One-Command Deploy
deploy.sh handles everything automatically: dependency check, data download, and strategy execution.
git clone https://github.com/AI4Finance-Foundation/FinRL-Trading.git
cd FinRL-Trading

# Backtest (downloads data + runs strategy)
./deploy.sh --strategy adaptive_rotation --mode backtest

# Custom date range
./deploy.sh --strategy adaptive_rotation --mode backtest --start 2020-01-01 --end 2025-12-31

# Single date signal
./deploy.sh --strategy adaptive_rotation --mode single --date 2024-12-31

# Paper trading (requires Alpaca credentials in .env)
./deploy.sh --strategy adaptive_rotation --mode paper --dry-run   # preview
./deploy.sh --strategy adaptive_rotation --mode paper              # execute

# See all options
./deploy.sh --help
Option B — Manual Setup with venv
# 1. Clone
git clone https://github.com/AI4Finance-Foundation/FinRL-Trading.git
cd FinRL-Trading

# 2. Create and activate virtual environment
python3 -m venv venv
source venv/bin/activate        # Linux / macOS
# venv\Scripts\activate         # Windows

# 3. Install dependencies
pip install -r requirements.txt

# 4. (Optional) Configure API keys for paper trading
cp .env.example .env
# Edit .env — set APCA_API_KEY, APCA_API_SECRET, etc.
Running Strategies via Python
# Backtest — Adaptive Rotation (2023-01-01 to 2024-12-31)
python src/strategies/run_adaptive_rotation_strategy.py \
    --config src/strategies/AdaptiveRotationConf_v1.2.1.yaml \
    --backtest --start 2023-01-01 --end 2024-12-31

# Single date signal
python src/strategies/run_adaptive_rotation_strategy.py \
    --config src/strategies/AdaptiveRotationConf_v1.2.1.yaml \
    --date 2024-12-31

# Full workflow tutorial (Jupyter)
jupyter notebook examples/FinRL_Full_Workflow.ipynb
Note: Data files (
{SYMBOL}_daily.csv) must exist underdata/fmp_daily/before running.deploy.shdownloads them automatically; for manual setup, either rundeploy.sh --strategy adaptive_rotation --mode backtestonce, or prepare CSV files with columnsdate,open,high,low,close,volume.
Configuration
cp .env.example .env
# Alpaca (required for paper/live trading)
APCA_API_KEY=your_key
APCA_API_SECRET=your_secret
APCA_BASE_URL=https://paper-api.alpaca.markets

# Data source (optional; Yahoo Finance is the free default)
FMP_API_KEY=your_fmp_key
Python API
# Data
from src.data.data_fetcher import get_data_manager
manager = get_data_manager()
prices = manager.get_price_data(['AAPL', 'MSFT'], '2020-01-01', '2024-12-31')

# Strategy
from src.strategies.ml_strategy import MLStockSelectorStrategy
strategy = MLStockSelectorStrategy(config)
result = strategy.generate_weights(data)

# Backtest
from src.backtest.backtest_engine import BacktestEngine, BacktestConfig
engine = BacktestEngine(BacktestConfig(start_date='2020-01-01', end_date='2024-12-31'))
result = engine.run_backtest("My Strategy", weights, prices)

# Live trade
from src.trading.alpaca_manager import create_alpaca_account_from_env, AlpacaManager
alpaca = AlpacaManager([create_alpaca_account_from_env()])
alpaca.execute_portfolio_rebalance(target_weights={'AAPL': 0.3, 'MSFT': 0.7})
Evolution from FinRL
| FinRL (2020) | FinRL-X (2026) | |
|---|---|---|
| Paradigm | DRL-only | AI-Native (ML + DRL + LLM-ready) |
| Architecture | Coupled monolith | Decoupled modular layers |
| Interface | Gym state/action spaces | Weight-centric contract |
| Data | 14 manual processors | Auto-select: Yahoo / FMP / WRDS |
| Backtesting | Hand-rolled loops | bt engine + multi-benchmark |
| Live Trading | Basic Alpaca | Multi-account + risk controls |
| Config | config.py |
Pydantic + .env |
| Paper | arXiv:2011.09607 | arXiv:2603.21330 |
Migration from FinRL
FinRL                                →  FinRL-X
─────────────────────────────────────────────────────────────
finrl/meta/data_processor.py         →  src/data/data_fetcher.py
finrl/train.py                       →  strategy.generate_weights()
finrl/trade.py                       →  TradeExecutor.execute_portfolio_rebalance()
config.py + config_tickers.py        →  src/config/settings.py (Pydantic + .env)
gym.Env subclassing                  →  BaseStrategy.generate_weights()
Comparison with Existing Platforms
| Feature | FinRL-X | Qlib | TradingAgents | Zipline/Backtrader | QuantConnect Lean |
|---|---|---|---|---|---|
| Primary Orientation | End-to-End System | ML Research | Agent-Based Trading | Backtesting | End-to-End Platform |
| Broker Integration | Yes | - | - | - | Yes |
| Deployment-Consistent Interface | Yes | - | - | - | Partial |
| Reinforcement Learning Support | Yes | Limited | Yes | - | Partial |
| Modular Strategy Pipeline | Yes | - | - | - | Partial |
| Portfolio-Level Risk Overlay | Yes | - | - | - | Partial |
| Open Source License | Apache 2.0 | MIT | Apache 2.0 | Apache 2.0 | Apache 2.0 |
Contributing
git checkout -b feature/your-feature
pip install -r requirements.txt
# make changes, add tests
git commit -m "Add: your feature"
git push origin feature/your-feature
# open a Pull Request
Adding a custom strategy:
from src.strategies.base_strategy import BaseStrategy, StrategyConfig, StrategyResult

class MyStrategy(BaseStrategy):
    def generate_weights(self, data, **kwargs) -> StrategyResult:
        # your alpha logic — return portfolio weights
        pass
Citation
@inproceedings{yang2026finrlx,
  title     = {FinRL-X: An AI-Native Modular Infrastructure for Quantitative Trading},
  author    = {Yang, Hongyang and Zhang, Boyu and She, Yang and Liao, Xinyu and Zhang, Xiaoli},
  booktitle = {Proceedings of the 2nd International Workshop on Decision Making and Optimization in Financial Technologies (DMO-FinTech)},
  year      = {2026},
  note      = {Workshop at PAKDD 2026}
}
License
Apache License 2.0 — see LICENSE.
Disclaimer
This software is for educational and research purposes only. Not financial advice. Always consult qualified professionals before making investment decisions. Past performance does not guarantee future results.
Explore related projects
codecrafters-io/build-your-own-x
Master programming by recreating your favorite technologies from scratch.
560,565 starspublic-apis/public-apis
A collective list of free APIs
496,834 starsmorluto/rea
Reverse engineer anything with agents, from app behavior down to native binaries.
439,199 starsopenclaw/openclaw
The AI that really does things. Any OS. Any Platform. The lobster way. 🦞
394,100 stars